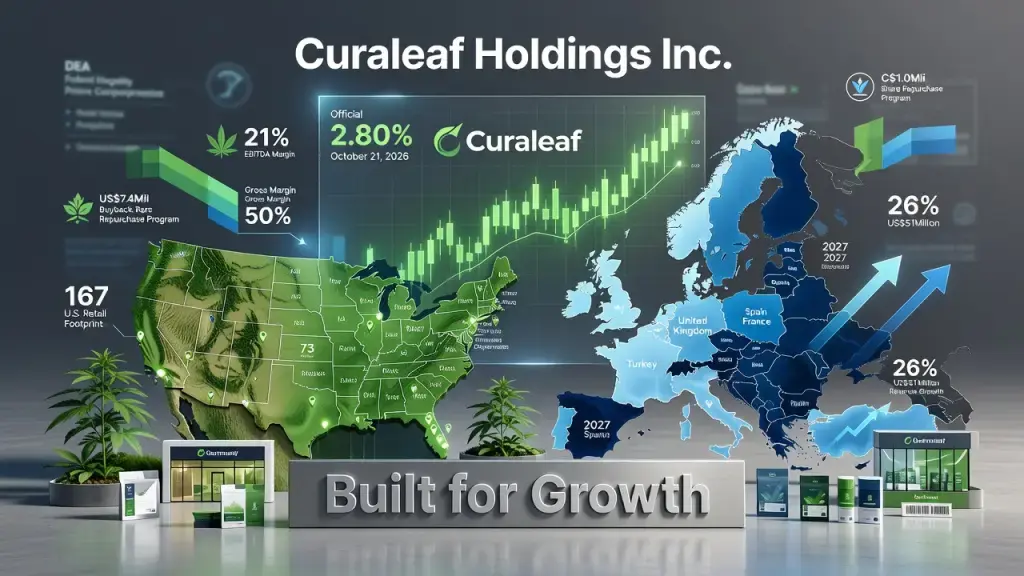
Curaleaf Holdings Inc. (TSX:CURA) rose 2.80% on October 21, 2026, continuing a recovery that began after its August report. There was no fresh news driving the session - the move looks like follow-through on a storyline investors have been warming to for weeks: a multi-state operator finally posting growth on both sides of the Atlantic at the same time.
Two Quarters of Domestic Growth, and What's Actually Behind It
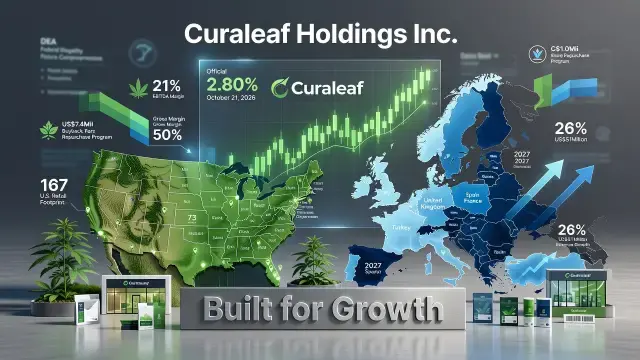
Domestic revenue climbed 7%, the second straight quarter of year-over-year gains in the U.S. business. That matters more than it might sound. American cannabis retail has spent the past few years absorbing price compression as mature adult-use markets like California, Colorado and Michigan saturated with license holders and wholesale menus got crowded. A multi-state operator stringing together two quarters of growth suggests the reset Chairman and CEO Boris Jordan has been pushing under the "Built for Growth" banner - built around customers, brands and operational execution - is showing up in the numbers rather than just the messaging. Florida has been a visible piece of that: the company's buyout of the remaining 45% stake in Four20 Pharma and its expansion to 73 dispensaries in that state pushed the total U.S. retail footprint to 167 locations. Florida remains one of the few large medical markets with meaningful adult-use conversion potential pending, which makes store count there worth watching closely for any multi-state operator positioning ahead of a possible ballot or legislative shift.
International Revenue Is Doing the Heavy Lifting
International revenue rose 26% to US$51 million, led by Germany, the United Kingdom and Poland. Curaleaf has flagged entry into Turkey, France and Spain for 2027. Europe's medical cannabis channel runs on different rails than U.S. retail - import licensing, pharmacy distribution and national reimbursement frameworks replace the dispensary-and-METRC model American operators know. That's a different compliance burden, not an easier one, but it comes without 280E, the federal tax provision that disallows standard business deductions for U.S. cannabis companies because the plant remains federally illegal. For a company reporting in U.S. dollars with roughly 71% retail and 28% wholesale revenue mix domestically, a growing European segment offers a tax structure that doesn't carry the same drag - a real structural advantage if the expansion holds.
Margins, Buybacks and the DEA Registration Overhang
Adjusted EBITDA margin came in at 21%, with gross margin around 50%, helped by cultivation efficiency and brand performance. That leaves room for operating leverage if domestic growth continues, though price compression in mature state markets remains the variable most likely to erode it. The company spent US$7.4 million on buybacks during the quarter and closed out a C$1.0 million repurchase program covering 93,363 shares - modest by most standards, but notable for a sector where cash preservation has often taken priority over returning capital to shareholders. Curaleaf does not pay a regular dividend and says it prioritizes debt management, growth investment and buybacks over distributions; sustained profitability and clearer regulatory footing would need to hold before that changes. Separately, the company is working through DEA registration for medical cultivation, processing and dispensing sites, a federal administrative process that operates independently of state licensing and can move on its own timeline.
Risks Operators and Investors Should Keep in View
- Federal illegality still restricts banking access and raises the cost of capital for U.S. cannabis businesses.
- Price compression in saturated adult-use markets can offset volume gains.
- State-by-state taxation, licensing fees and compliance costs vary widely and add administrative load.
- European expansion depends on regulatory approvals in each new country, which can slip or stall.
- Cannabis equities remain prone to sharp sentiment swings unrelated to underlying fundamentals.
None of this changes the basic consumer-safety framework that governs the retail side of the business: products sold through licensed dispensaries are subject to lab testing, compliant packaging and age-restricted sale rules that vary by state and, in Europe, by national medical regulation. For operators and suppliers watching Curaleaf as a bellwether, the questions worth tracking are straightforward - does domestic growth persist into a third quarter, do the announced European entries actually clear regulatory review on schedule, and does margin improvement survive continued wholesale price pressure. A cautiously constructive read seems fair. Confirmation will come from the next few reporting cycles, not from a single session's price move.